What Underwriters Actually Look For in Surety Bond Applications
Underwriters evaluate your financial stability, credit score, and business experience to determine your risk level. They analyze your ability to fulfill the bond's obligations, not just your desire to obtain it. Gerald Franklin Agency helps you prepare these documents so your application moves quickly through the approval process.
Financial Stability and Liquidity
Underwriters prioritize your balance sheet to ensure you can cover potential claims. They look for consistent cash flow and adequate working capital. A strong liquidity position signals that your business can absorb unexpected costs without defaulting on the bond.
For example, a restaurant applying for a conduct surety bond must show it can maintain operations even if a claim arises. Underwriters review bank statements and profit and loss statements to verify this stability. If your financials are weak, you may need to provide additional collateral or a co-signer.
Credit Profile and History
Your personal and business credit scores are primary indicators of reliability. Underwriters use these scores to gauge your likelihood of paying premiums and fulfilling obligations. A high credit score often results in lower premiums and faster approval.
Consider a business owner with a credit score of 750 or higher. This profile typically qualifies for standard terms without extra scrutiny. Conversely, a lower score may trigger a manual review, requiring you to explain any negative items. Gerald Franklin Agency works with surety companies that serve applicants with varying credit profiles to find the right fit.
Business Experience and Track Record
Underwriters assess how long you have operated in your industry. They want to see a history of successful compliance and minimal claims. Newer businesses face higher scrutiny because they lack a proven track record.
A business operating for five years with no prior bond claims presents a lower risk profile. Underwriters may request references from past clients or partners to verify your reputation. This experience demonstrates your understanding of industry regulations and your commitment to ethical operations.
Legal Compliance and Background
Legal history is a critical factor in underwriting decisions. Underwriters check for past violations, lawsuits, or regulatory actions. A clean legal record supports a smooth approval process.
If you have a history of alcohol license violations, underwriters will scrutinize your corrective actions. They want to see evidence that you have addressed past issues and implemented new controls. Transparency about any legal matters is essential to building trust with the surety company.
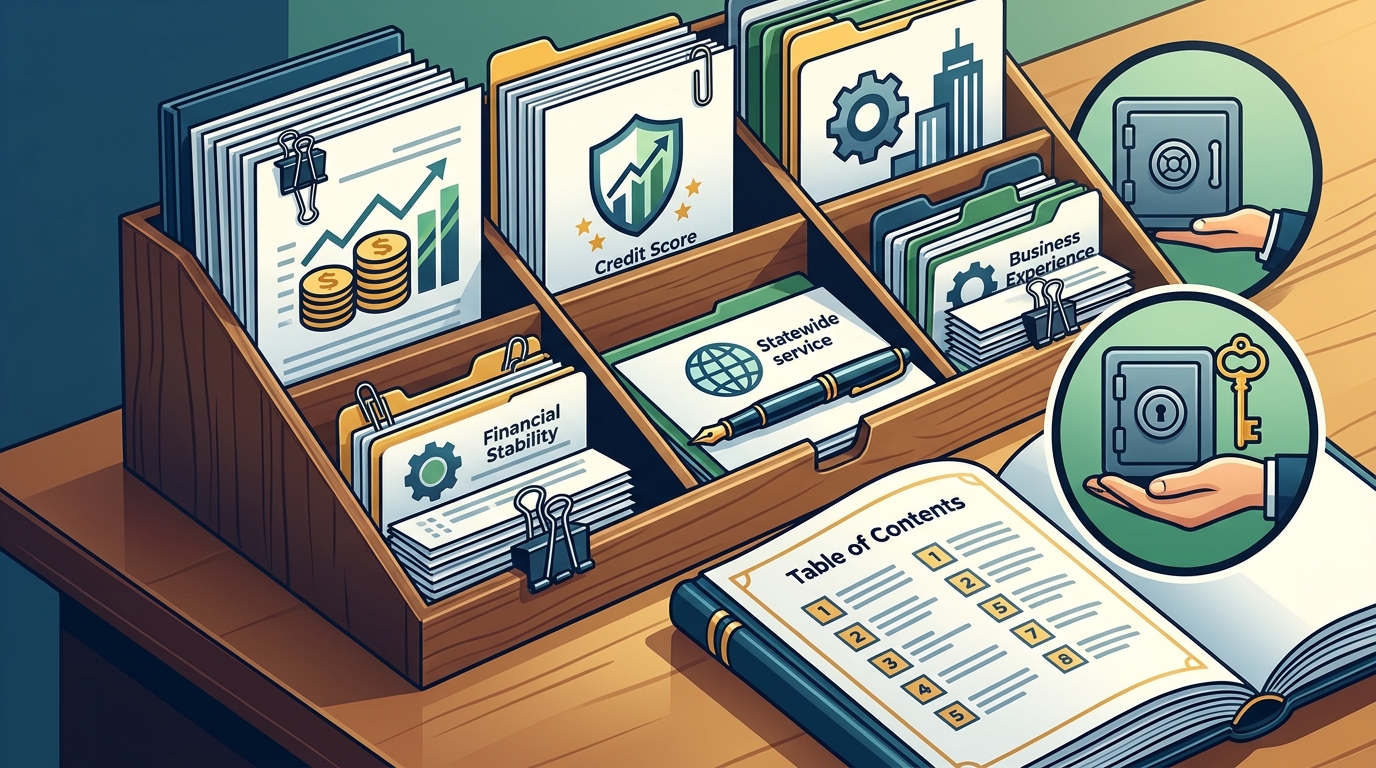
Risk Mitigation Strategies
Underwriters look for proactive steps you have taken to reduce risk. This includes insurance coverage, internal controls, and compliance training. Demonstrating these measures shows you are committed to preventing claims.
For instance, a liquor store might implement strict inventory tracking and employee training programs. These steps reduce the likelihood of theft or regulatory violations. Underwriters view such initiatives as positive indicators of your management quality.
Key Takeaways
- Financial stability is the primary factor in bond approval.
- Credit scores significantly impact premium rates and approval speed.
- Business experience and a clean track record reduce perceived risk.
- Legal compliance history is thoroughly reviewed by underwriters.
- Proactive risk mitigation strategies can improve your application.
- Working with an experienced agency can streamline the process.
Frequently Asked Questions
What is a surety bond?
A surety bond is a three-party contract between your business, the surety company, and the obligee that guarantees compliance with specific laws or regulations.
How long does underwriting take?
Underwriting typically takes a few days to a few weeks, depending on the complexity of your financials and credit profile.
Can I get a bond with bad credit?
Yes, but you may face higher premiums or need to provide collateral. Working with an agency that has relationships with multiple sureties can help.
What documents do I need?
You generally need financial statements, credit reports, and business formation documents. Specific requirements vary by bond type.
Does a bond protect my business?
A bond protects the public and the state, not your business directly. However, maintaining a bond can enhance your credibility and compliance standing.
Start Your Application with Confidence
Understanding what underwriters look for helps you prepare a stronger application. Gerald Franklin Agency has managed alcohol licensing since 1944 and knows exactly what surety companies require. We issue bonds in-house and file them directly into the TABC AIMS portal, ensuring your permit stays on schedule. To plan your visit, to discuss your specific bond needs.