What Are the Requirements for a Surety Bond in Texas?
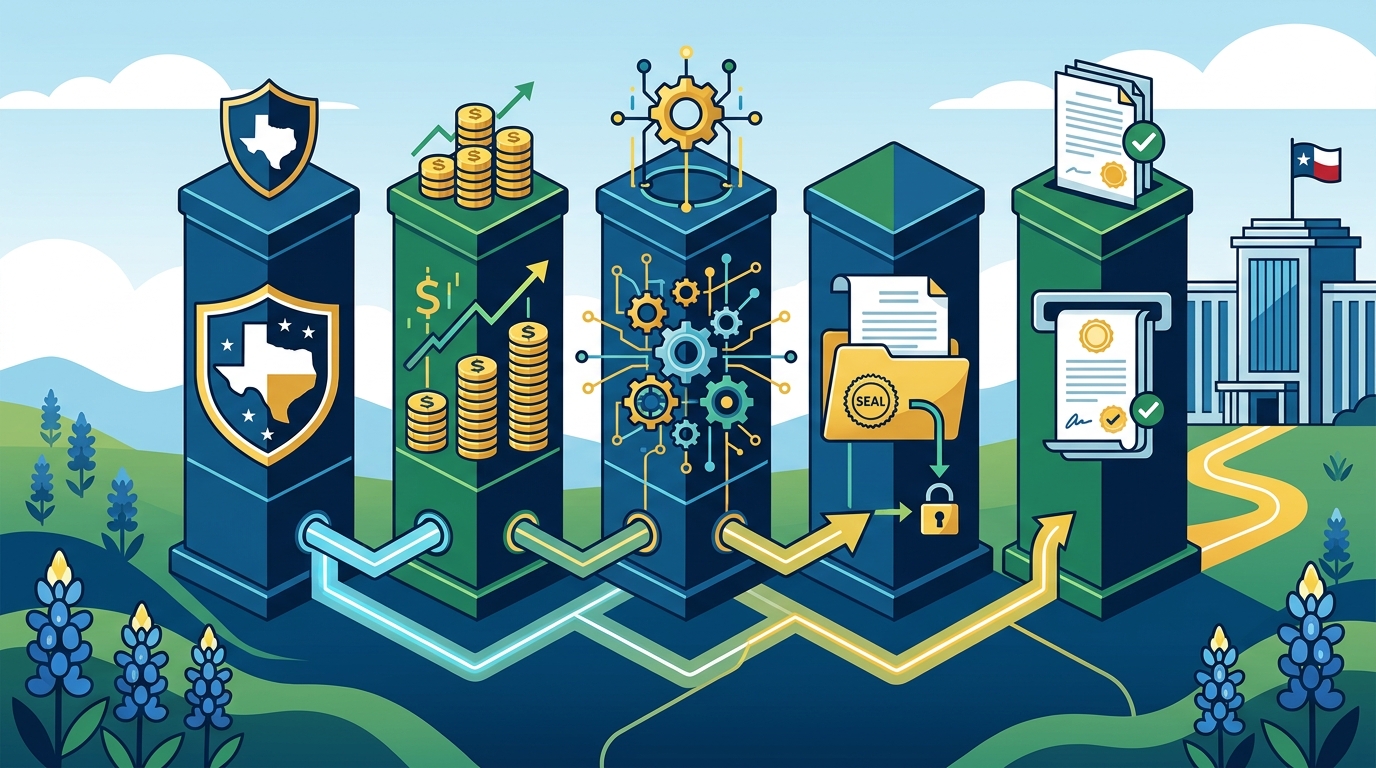
A Texas surety bond is a three-party financial guarantee that protects the public or the state from financial loss due to non-compliance with specific laws or regulations. The core requirements for a surety bond in Texas include obtaining authorization from the Texas Department of Insurance, meeting specific bond amount thresholds, satisfying underwriting criteria, and filing the bond with the correct obligee. This guide covers the five critical steps to securing a bond in Texas, from initial authorization to final filing procedures.
Surety Company Authorization
Before a business can purchase a bond, the surety company issuing it must be legally authorized to operate in Texas. A surety company is an insurance company that guarantees the performance of an obligation by a third party. In Texas, all surety companies must be licensed by the Texas Department of Insurance (TDI). This authorization ensures that the company meets strict financial stability and regulatory standards, protecting the principal and the obligee from the risk of the surety failing to pay a valid claim.
Verifying License Status
Businesses should verify that their chosen surety provider is active and in good standing with the TDI. The TDI maintains a public database of licensed insurance companies. Using an unauthorized or out-of-state surety that has not obtained a Texas license can result in the bond being rejected by the obligee. Gerald Franklin Agency works exclusively with licensed, A-rated surety providers to ensure that every bond issued to our clients is fully compliant with state regulations.
Admitted vs. Non-Admitted Carriers
Most Texas bonds are issued by admitted carriers, which are regulated by the state and subject to its solvency requirements. Non-admitted or surplus lines carriers may be used in specific circumstances, but for standard commercial and regulatory bonds, an admitted carrier is the standard requirement. Ensuring the carrier is admitted simplifies the filing process and provides an additional layer of regulatory oversight.
Bond Amount Requirements
The bond amount is the maximum financial liability the surety assumes if the principal fails to meet their obligations. In Texas, bond amounts are not arbitrary; they are typically dictated by the specific statute, regulation, or contract requiring the bond. A bond amount is the specific dollar value stated on the bond form that represents the total financial guarantee provided to the obligee.
Statutory vs. Contractual Amounts
Scaling with Business Volume
Some bond amounts scale with the volume of business or the value of transactions. For instance, a liquor and beer tax bond is often set based on an estimate of six weeks of excise tax liability. As a business grows, the TABC may require an increase in the bond amount to reflect the higher tax liability. Gerald Franklin Agency monitors these changes and handles the necessary bond increases to keep your permits in good standing.
Obligee Specifications
The obligee is the party that benefits from the bond and to whom the bond is issued. In the context of Texas regulatory bonds, the obligee is usually a state agency, such as the Texas Alcoholic Beverage Commission (TABC) or the Texas Department of Licensing and Regulation (TDLR). An obligee is the entity that receives the financial protection provided by the surety bond in case of a default by the principal.
Identifying the Correct Agency
Each type of bond has a specific obligee. For alcohol-related permits, the TABC is the obligee. For contractor licenses, the TDLR is the obligee. Filing a bond with the wrong agency will result in rejection and delays. The bond form must explicitly name the correct obligee as defined by the governing statute. Our team at Gerald Franklin Agency ensures that the obligee is correctly identified on every application to prevent administrative errors.
Submission Requirements
Obligees have specific requirements for how the bond is submitted. Some agencies require the bond to be filed through an online portal, such as the TABC's AIMS system, while others may accept physical copies or electronic filings through specific third-party platforms. The bond must be in the exact format required by the obligee, including specific wording and signature blocks. Failure to meet these specifications can lead to the bond being deemed invalid.
Underwriting Criteria
Underwriting is the process by which a surety company evaluates the risk of issuing a bond. Underwriting criteria are the specific factors a surety company uses to assess the financial stability and character of the principal to determine if they are eligible for a bond. The principal is the business or individual who purchases the bond and is legally obligated to perform the duties specified in the bond.
Financial Statements and Credit
Surety companies typically require personal and business financial statements, including balance sheets and income statements. They also consider the personal credit score of the business owner. A strong credit history and solid financials demonstrate the ability to fulfill the bond's obligations. If a business has poor credit, the surety may require a collateral deposit or a higher premium to mitigate the risk.
Experience and Industry Standing
For professional and contractor bonds, the surety will evaluate the principal's experience in the industry. This includes the number of years in business, past performance, and any history of claims or violations. A clean record with regulatory agencies, such as the TABC, significantly improves the chances of approval and can lead to lower premiums. Gerald Franklin Agency helps clients prepare the necessary documentation to present a strong underwriting profile.
Filing Procedures
Once the bond is approved and issued by the surety, it must be filed with the obligee to become active. Filing procedures are the specific steps required to submit the executed bond to the regulatory agency or contracting party. Proper filing is the final step in the bonding process and is essential for the bond to be legally effective.
Online vs. Physical Filing
Many Texas agencies, including the TABC, have moved to digital filing systems. The TABC uses the AIMS (Alcoholic Beverage Information Management System) portal for filing permits and bonds. The bond must be uploaded or linked within this system. For other agencies, physical filing may still be required, involving the submission of the original signed bond document to the agency's office. Knowing the correct filing method is crucial to avoid delays.
Tracking and Confirmation
After filing, the principal should obtain a confirmation or receipt from the obligee. This document serves as proof that the bond has been accepted and is active. It is important to keep this record for your business files. Gerald Franklin Agency manages the entire filing process, from issuing the bond to confirming its acceptance by the TABC or other relevant agencies, ensuring that your business is fully compliant and ready to operate.
Key Takeaways
- Surety companies must be licensed by the Texas Department of Insurance to issue bonds in the state.
- The obligee is the regulatory agency or entity that benefits from the bond and must be correctly named on the form.
- Underwriting criteria include financial statements, credit scores, and industry experience to assess risk.
- Filing procedures vary by agency, with many Texas regulators now requiring digital submission through online portals like AIMS.
- Proper filing and confirmation are essential for the bond to be legally active and for the business to operate in compliance.
- Gerald Franklin Agency handles the entire process, from authorization to filing, ensuring accuracy and compliance.
Frequently Asked Questions
Who is the obligee for a Texas liquor license bond?
The obligee for a Texas liquor license bond is the Texas Alcoholic Beverage Commission (TABC). The bond is filed with the TABC as part of the permit application process.
How much is a conduct surety bond in Texas?
Do I need a personal guarantee for a business bond?
Yes, most surety bonds require a personal guarantee from the business owner or principal. This means the individual is personally liable if the business fails to meet the bond's obligations.
How long does it take to get a surety bond in Texas?
With a clean credit history and complete documentation, a surety bond can often be issued within 24 to 48 hours. Filing with the agency may take additional time depending on their processing schedule.
Can I use any insurance company to get a bond?
No, the insurance company must be a licensed surety company authorized to do business in Texas. Using an unauthorized company will result in the bond being rejected by the obligee.
What happens if a claim is made against my bond?
If a valid claim is made, the surety company pays the claim up to the bond amount. The principal is then responsible for reimbursing the surety for the amount paid, plus any investigation costs.
Does Gerald Franklin Agency handle bond filing?
Yes, Gerald Franklin Agency handles the entire process, including issuing the bond with a licensed surety and filing it with the TABC or other relevant Texas agencies.